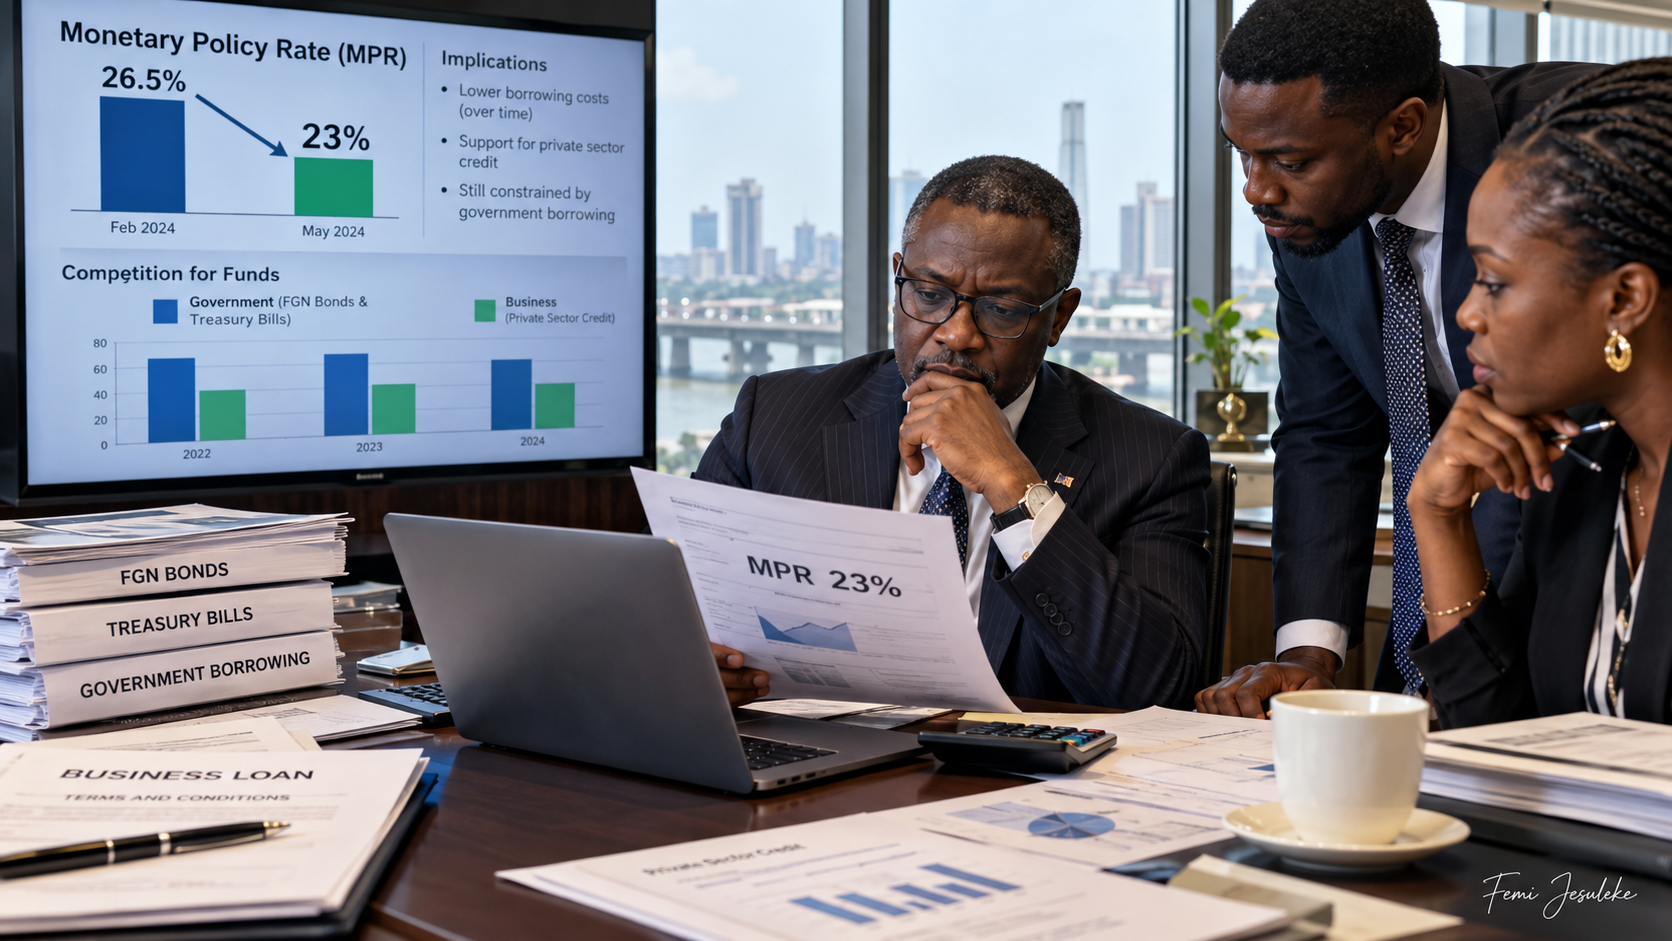
The Central Bank of Nigeria has reduced the Monetary Policy Rate from 26.5% to 23%. That is a significant move. It is also reasonable for business owners to ask whether their loans will now become cheaper.
The answer is possibly, but not immediately and not automatically.
The MPR guides the general direction of interest rates. A reduction of 350 basis points should gradually lower the cost of some forms of borrowing. However, banks do not price corporate loans from the MPR alone.
They also consider their cost of deposits, available liquidity, the borrower’s credit quality, collateral, capital requirements, operating costs and the return available from other assets.
The competition for money remains
Government securities remain one of the strongest alternatives to corporate lending. The Federal Government continues to issue Treasury bills and bonds through regular auctions.
A bank deciding whether to lend to a manufacturer or buy government paper will compare the expected return with the risk and work involved.
A corporate loan requires credit analysis, collateral review, monitoring and recovery effort if the borrower defaults. It also uses regulatory capital. Government securities do not carry the same level of corporate credit risk.
A lower MPR does not automatically end crowding out. Government and businesses are still competing for finance.
Government may benefit first
If Treasury bill and bond yields decline, the Federal Government may be able to borrow at a lower cost. That would reduce some pressure on debt service.
Banks and existing borrowers with facilities that reprice may benefit next. Businesses seeking new credit may have to wait longer because transmission through the banking system can be slow.
The Manufacturers Association of Nigeria has warned that the effect may remain limited while commercial lending rates stay close to 30%. The concern is valid. A policy rate can fall without making finance affordable for the average manufacturer.
The 45% cash reserve requirement still matters
The CBN retained the Cash Reserve Requirement for deposit money banks at 45%. In simple terms, banks must still keep a large share of eligible deposits with the central bank.
This limits the amount that can be freely deployed. The monetary policy message is therefore mixed. The price signal has improved, but liquidity remains tight.
Businesses should not expect bank lending rates to fall by the full 350 basis points simply because the MPR did.
Lower inflation does not mean lower prices
Nigeria’s headline inflation eased to 15.39% in August 2026 from 15.43% in July. The monthly rate also slowed to 0.71%. The National Bureau of Statistics published the August figures here.
This is encouraging, but it does not mean business costs have returned to earlier levels. It means prices are rising more slowly.
If an input moved from ₦100 to ₦170 during the high inflation period, slower inflation does not return it to ₦100. It means the increase from ₦170 becomes slower.
Fuel, power, transport, wages, imported materials, insurance and logistics remain expensive. Petrol recently reached about ₦1,400 per litre in Lagos and Abuja, while diesel moved above ₦2,000 per litre. Reuters reported the recent fuel price pressure here.
Lower inflation, high operating costs and expensive credit can exist at the same time. A lower MPR alone will not repair company margins.
Repair the balance sheet before expanding it
Some companies may now assume that cheap money is coming and begin planning aggressive expansion. That may be premature.
Management should first identify debt that was priced during the peak rate period. It should then assess whether expensive short term facilities can be replaced with longer funding at a lower effective cost.
Companies should also determine whether they have a financing problem or a working capital problem. A business with ₦5 billion trapped in receivables may not need another ₦5 billion loan. It may need better collection discipline. A business carrying excessive inventory may need better stock management, not more debt.
Watch the rates that companies actually pay
The most important numbers over the next few months will not be the MPR alone. CFOs should track:
- Treasury bill stop rates;
- Federal Government bond yields;
- commercial bank lending rates;
- commercial paper yields;
- corporate bond pricing; and
- private credit pricing.
These figures will show whether monetary easing is reaching businesses. The real test is whether a credible manufacturer that previously borrowed at 30% can obtain funding at 25%, 22% or lower.
Fiscal policy is part of the answer
If government continues to borrow heavily from the domestic market, banks, pension funds and insurers will still have strong incentives to hold government paper.
The CBN determines the monetary policy stance, but fiscal authorities influence how much the government needs to borrow. Large fiscal deficits can therefore sustain crowding out even when policy rates are falling.
If the chain stops after government borrowing becomes cheaper, businesses may see little benefit.
Companies must also become more bankable
Not every funding problem can be blamed on the financial system. Banks and institutional investors will respond more positively to companies with reliable audited accounts, predictable cash flow, sound governance, manageable leverage, suitable security and a clear repayment source.
CFOs should use this period to improve cash forecasting, collect receivables, reduce unnecessary short term borrowing, restructure foreign currency exposures and prepare dependable financial information.
The CBN’s decision is directionally positive. However, Nigeria has not yet entered an era of cheap business credit.
The number that matters most is not the MPR. It is the actual rate at which your business can borrow.
That rate will tell us whether the 23% MPR is only a headline or the beginning of real relief for Nigerian businesses. The CBN’s current and previous policy decisions are available on its monetary policy page.